How to Choose Travel Insurance for Australians Over 60
Travel insurance becomes an important part of planning an overseas trip, particularly as you get older.
But finding the right policy can be confusing.
Age limits, pre existing medical conditions, cruises, cancellation cover, excesses and exclusions can vary considerably between insurers.
The cheapest policy is not necessarily the right one, and the policy that worked for a friend may not suit your circumstances.
Here is what Australians over 60 should look at before buying travel insurance.
Why Travel Insurance Matters
Medicare generally does not cover Australian travellers overseas, although Australia does have reciprocal healthcare agreements with some countries.
Even where an agreement exists, it may not cover everything you need.
The Australian Government also cannot pay your overseas medical bills if something goes wrong.
Smartraveller recommends Australians travelling overseas take out appropriate travel insurance for their circumstances.
1. Start With Your Health
For many travellers over 60, this is one of the most important parts of choosing a policy.
A pre existing medical condition may be automatically covered, require assessment or an additional premium, or be excluded.
Different insurers can treat the same condition differently.
Do not assume a condition is too minor to matter.
Smartraveller recommends declaring your medical conditions and checking directly with the insurer if you are unsure whether something is covered.
This can include physical and mental health conditions.
2. Check the Age Conditions
There is no universal age limit for travel insurance.
Some policies accept much older travellers than others, and age can affect more than whether you are eligible.
Depending on the policy, older travellers may face:
Higher premiums
Higher excesses
Different medical limits
Medical assessments
Restrictions on trip duration
Different conditions of cover
That makes reading the policy conditions particularly important rather than assuming a policy marketed to travellers generally will suit someone in their 70s or 80s.
3. Look Closely at Overseas Medical Cover
Medical cover should be one of the first things you compare.
Check what the policy covers for:
Hospital treatment
Emergency medical treatment
Medical evacuation
Repatriation to Australia
Existing medical conditions
Smartraveller notes that medical cover is the number one reason to purchase travel insurance and that many policies offer an unlimited medical sum insured.
Rather than looking for an arbitrary dollar amount, compare the actual medical benefits and exclusions offered by each policy.
4. Think About Cancellation Cover
A big overseas holiday can involve thousands of dollars in flights, accommodation, tours and cruises before you even leave Australia.
Cancellation cover may help with certain unexpected events, but it does not mean you can cancel for any reason.
Look at:
The maximum cancellation benefit
What events qualify
Exclusions
Rules involving illness or injury
Conditions relating to relatives
What happens if travel advice changes
Smartraveller also recommends buying insurance once you know your travel dates and have booked and paid for the trip, because relevant cancellation cover can then begin before departure.
5. Going on a Cruise? Check Cruise Cover
Do not assume an ordinary international policy automatically provides everything you need for a cruise.
Depending on the policy, cruise related cover may address things such as:
Medical treatment onboard
Medical evacuation
Cabin confinement
Missed ports
Cancellation
Prepaid excursions
The important part is checking exactly what the policy includes rather than simply seeing the word “cruise” on the website.
6. Check Your Planned Activities
What are you actually going to do on holiday?
Walking around Rome is very different from skiing, riding a motorcycle or doing adventure activities.
Some policies exclude particular activities or require additional cover.
Moneysmart recommends considering your destination and planned activities and checking that they are included before purchasing the policy.
7. Do Not Forget Your Belongings
Medical expenses might be the biggest concern, but also check what happens to your luggage and valuables.
Look at:
Individual item limits
Phones and tablets
Cameras
Jewellery
Mobility equipment
Unattended belongings
Checked luggage
Smartraveller warns that coverage for valuables varies considerably and that unattended belongings are generally not covered.
If you are travelling with expensive equipment, make sure the individual item limits are actually sufficient.
8. Check the Excess
A cheaper premium can sometimes come with a higher excess.
The excess is the amount you may need to contribute when making a claim.
Moneysmart recommends checking both the premium and whether you could comfortably afford the excess if something went wrong.
For older travellers, this deserves particular attention because some policies apply higher excesses above certain ages.
9. Compare More Than the Price
Two policies costing similar amounts can provide very different protection.
When comparing policies, look at:
Medical cover
Pre existing conditions
Age restrictions
Cancellation
Medical evacuation
Cruise cover if relevant
Activities
Baggage
Excess
Trip duration
Emergency assistance
Exclusions
Then compare the price.
Shopping around can be worthwhile because premiums vary according to factors including destination, age, health and planned activities.
10. Read the PDS
This is probably the least exciting part of planning your holiday, but it is one of the most important.
The Product Disclosure Statement explains what the policy actually covers and excludes.
Do not rely entirely on the marketing page or comparison table.
Pay particular attention to:
Pre existing medical conditions
Age restrictions
Medical cover
Cancellation
Activities
Cruises
Alcohol related exclusions
Unattended belongings
Travel warning exclusions
Moneysmart specifically recommends reading the PDS carefully before choosing your cover.
What About Credit Card Travel Insurance?
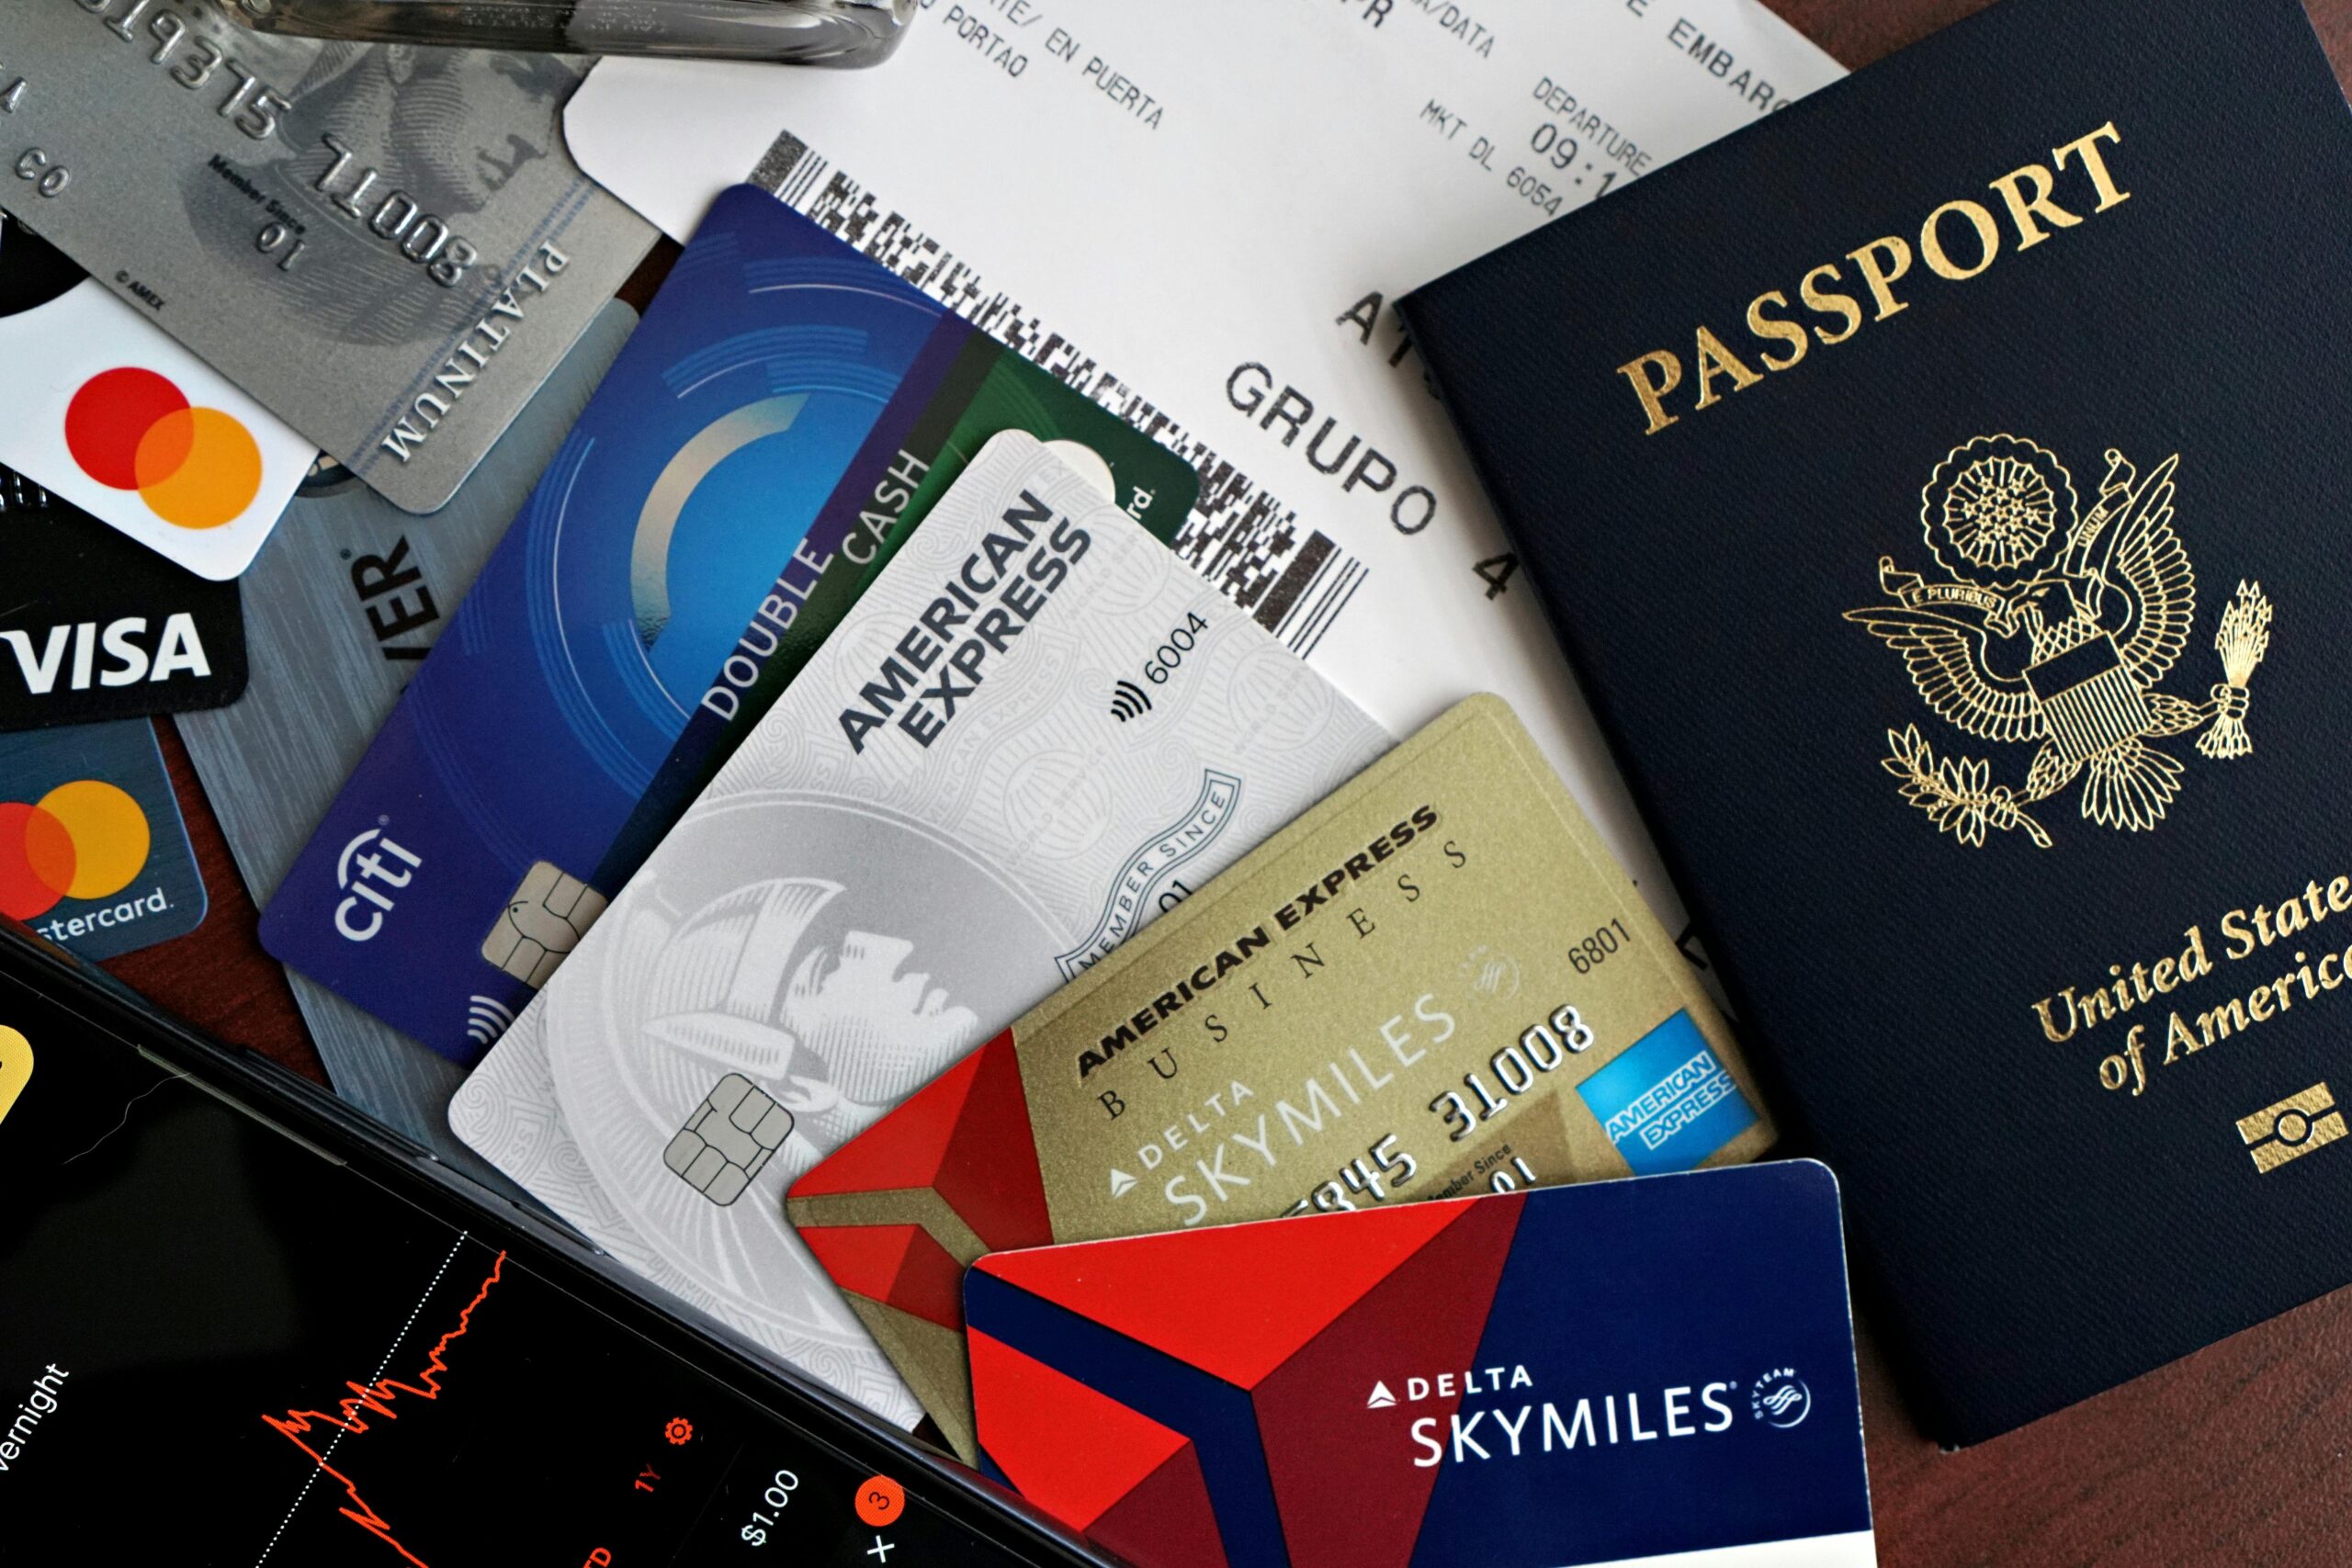
If your credit card includes complimentary travel insurance, do not automatically assume you need another policy.
But do not automatically assume the credit card cover is enough either.
Check how the insurance is activated, trip duration limits, age conditions, medical conditions, excesses and what expenses must be paid using the card.
Credit card policies can provide substantial cover, but their conditions vary.
What Is the Best Travel Insurance for Australians Over 60?
There is no single insurer that is best for every Australian over 60.
Someone aged 62 taking a two week holiday to New Zealand with no medical conditions has very different insurance needs from someone aged 79 with existing medical conditions taking a three month cruise.
Instead of starting with:
Which insurer is cheapest?
Start with:
Which policy actually covers my trip, my health and the things I plan to do?
Then compare the price.
That is a much safer way to choose.
Before You Buy
Before paying for a policy, make sure you understand:
Your declared medical conditions
Where you are covered
How long you are covered
What activities are included
Your medical cover
Your cancellation limit
Your excess
Your baggage limits
Any cruise requirements
Major exclusions
How to contact the insurer in an emergency
How to make a claim
If anything is unclear, ask the insurer before purchasing and keep a record of the information you receive.
Travel With Confidence
Travel insurance is not the most exciting part of planning a holiday.
But understanding your cover before you leave can prevent an unpleasant surprise when you actually need it.
Compare several policies, disclose relevant medical conditions, read the PDS and choose cover based on your individual trip rather than simply choosing the cheapest quote.
For more practical advice before heading overseas, read our guide:
And our complete overseas travel guide:
Have you ever needed to make a travel insurance claim while overseas? What did you learn from the experience?